6 May 2026 · Enric Massó · Money & Risk
Seny Is Not the Opposite of Taking Risks
There is a version of prudence that looks very sensible from the outside. You wait until you know more. Then you wait because conditions are uncertain. Then because prices are high, low, volatile or suspiciously calm. Eventually you…
Catalan has a useful word for practical judgement: seny. It is usually translated as common sense, prudence or sound judgement, although none of those quite captures it. The interesting part is what happens when we confuse it with caution. Caution says: avoid the risk. Seny should be asking: what risk am I taking, what happens if I am wrong, and can I live with it? Those are very different questions.
Money makes the confusion particularly easy because losses are visible. If you invest and the value falls, you can see the mistake on a screen. If you leave everything untouched for years and inflation slowly reduces what the money can buy, the loss is quieter. If you avoid changing jobs, starting a business, paying down expensive debt or making a necessary investment because uncertainty feels uncomfortable, there may never be a neat number showing what inaction cost. We tend to count active decisions more carefully than passive ones.
Doing nothing is also a position
This does not mean that everyone should invest, take more risk or become adventurous with money. Sometimes doing nothing is exactly right. Cash that you may need soon has a different job from money you will not touch for fifteen years. A household without a financial cushion has a different problem from one deciding where to put long-term savings. Expensive debt changes the calculation again.
The useful habit is to stop treating “no action” as neutral. Every choice has a trade-off. Keeping money accessible sacrifices potential return in exchange for liquidity and certainty. Investing accepts volatility in exchange for the possibility of long-term growth. Paying extra for insurance transfers part of a risk at a price. Avoiding debt reduces exposure but may also limit what you can do. None of these positions is automatically sensible outside its context.
That is where seny becomes more demanding than simple caution. It requires judgement. And judgement is uncomfortable because there is no universal number that tells you when a risk becomes acceptable. Two people can understand exactly the same investment and reasonably choose differently because one may need the money, sleep badly when markets fall, have insecure income or simply value certainty more.
Financial decisions happen inside a life, not inside an optimisation model.
Rauxa has a job too
The traditional companion to seny is rauxa: impulse, boldness, the moment when restraint gives way to action. It is tempting to treat the two as enemies, with one sitting on each shoulder like a particularly Catalan cartoon. I find the relationship more useful if they work together.
Seny should decide whether the downside is understood and survivable. Rauxa is what occasionally gets you to act once you have spent enough time thinking. Without the first, risk becomes recklessness. Without the second, prudence can become a very respectable way of standing still.
This applies well beyond investing. Starting a business, changing career, buying a home, paying for training or deciding not to pursue an opportunity all involve uncertain futures. Waiting for uncertainty to disappear is not a strategy because uncertainty is often the thing you are deciding about.
A sensible decision is not one that guarantees a good outcome. That standard is impossible. It is one where the reasoning still makes sense even if the outcome later disappoints you.
That distinction matters. We judge financial decisions far too easily by what happened afterwards. A reckless gamble that worked can look intelligent. A carefully considered decision that met an unlikely bad outcome can look foolish. Results matter, but they are not the same thing as decision quality.
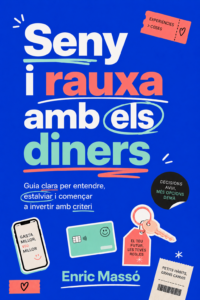
While writing Seny i rauxa amb els diners, I wanted to keep returning money to this more ordinary territory. Before products, returns and clever strategies comes something less glamorous: understanding your margin, protecting yourself from obvious damage, and deciding which uncertainties you are actually willing to live with.
Perhaps that is the useful balance. Seny does not tell you never to jump. It makes you look down first.
Related book
Seny i rauxa amb els diners Guia clara per entendre, estalviar i començar a invertir amb criteri
A practical introduction to managing money before chasing returns: understanding your real margin, building protection, saving with purpose and approaching investment with context rather than hype.
Available on Amazon → [link pending]